
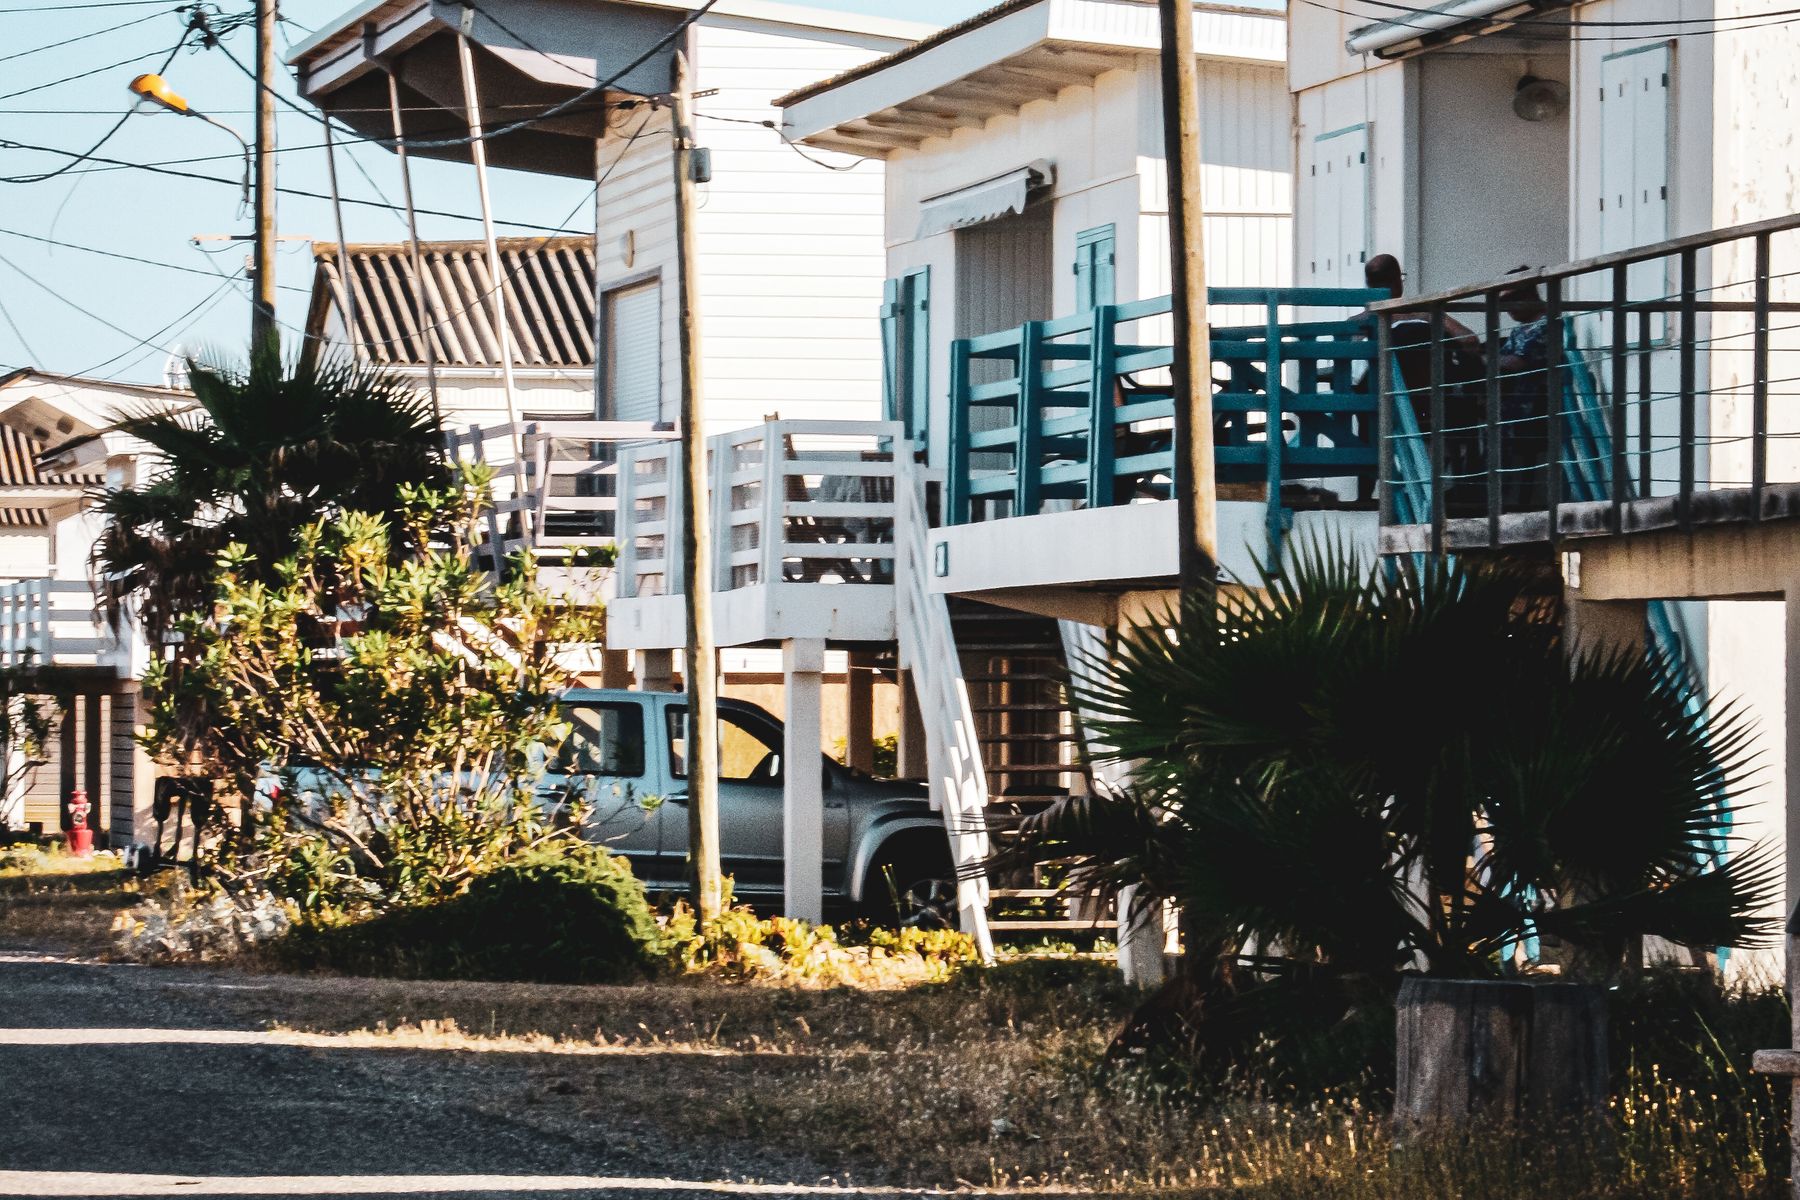
No law requires an elevation certificate to sell a home in a flood zone in North Carolina, and since Risk Rating 2.0 your buyer does not need one to get an NFIP quote either. You still want one, because it is the cheapest thing you can do to keep a flood zone listing from losing its buyer over an insurance number.
We get this question from sellers in Ogden, on Masonboro Sound, in the Carolina Beach bungalows and anywhere the FEMA map clips the back of a lot. The worry behind it is always the same: that the flood zone itself is going to cost them the sale. It usually does not. What costs the sale is a buyer who gets a scary premium quote in week two of due diligence and has nothing to check it against.
What changed, and why are sellers confused?
Until October 2021, an elevation certificate was how the National Flood Insurance Program priced an elevated building, so a certificate was close to mandatory in practice. Under Risk Rating 2.0, FEMA’s own guidance is explicit that a certificate is no longer required to purchase coverage, and that FEMA uses its own tools and data to estimate a building’s elevation instead.
That is where most of the confusion comes from. Sellers hear “no longer required” and conclude the document is obsolete. It is not. FEMA’s guidance also says a policyholder may obtain an elevation certificate, which gives more refined elevation information, and submit it to see whether it lowers the rate. The useful detail for a seller is the asymmetry: FEMA uses submitted elevation data when it produces a better rate and disregards it when it does not, and if the certificate comes in after the policy starts and lowers the rate, the premium is adjusted with a refund prorated back to the policy’s effective date. In plain terms, a certificate can only help your buyer’s number. It cannot hurt it.
Does the North Carolina disclosure form ask about it?
Yes. The Residential Property and Owners’ Association Disclosure Statement, the form the North Carolina Real Estate Commission prescribes under rule 21 NCAC 58A .0114, has carried flood items since the Commission amended the rule in 2023 following a 2022 petition. Those items include whether the property lies in a Special Flood Hazard Area and whether an elevation certificate exists for it. We could not pull the current PDF from the Commission’s site on the day we wrote this, so check the exact wording on the form your broker hands you.
Here is the part sellers get wrong. For every item on that form, North Carolina gives you three answers: Yes, No, or No Representation. Checking No Representation down the flood section feels safe. It is not. A flood zone designation is public record, the buyer’s lender will find it, and in our experience a page of No Representation on a coastal listing does one thing reliably: it makes buyers order more inspections and negotiate harder. If a certificate exists, say so and hand it over. If one does not exist, say that too.
What is the certificate actually worth on a Wilmington-area listing?
It is worth whatever the premium difference is, multiplied by the buyer’s willingness to stay in the deal. The flood insurance number is not the same across our market, because the discount attached to your town is not the same.
- Community Rating System class 6, a 20 percent premium discount: Carolina Beach, Oak Island, Topsail Beach, Holden Beach, Sunset Beach FEMA Community Status Book, North Carolina, September 2026
- Class 7, a 15 percent discount: New Hanover County, Pender County, Wrightsville Beach, Leland, Southport, Bald Head Island FEMA Community Status Book, North Carolina, September 2026
- Class 8, a 10 percent discount: Brunswick County, Kure Beach, Caswell Beach FEMA Community Status Book, North Carolina, September 2026
- City of Wilmington: no CRS class listed, so no CRS discount FEMA Community Status Book, North Carolina, September 2026
- New Hanover County listings take a median 58 days to go under contract, against 37 days a year earlier, with 1,249 active listings Tidal Realty Partners New Hanover County market update, three months ending August 2026
Read the last line with the rest. Your buyer has about 1,249 other options and the market is giving them 58 days to think. Anything that turns a flood question into a document shortens that thinking. We have watched a single PDF hold a deal together when the first insurance quote came back high and the agent could send the certificate to a second carrier the same afternoon.
Do I already have one without knowing it?
If the house was built or substantially improved after your community joined the flood program, a certificate was almost certainly filed with the local floodplain administrator when it was built. In New Hanover County, floodplain development is permitted through Planning and Land Use under Article 9 of the Unified Development Ordinance, and that office is where the file lives. Call the floodplain administrator with the address before you pay a surveyor. Brunswick and Pender counties and each of the beach towns keep their own files, so the right phone call depends on which jurisdiction the house sits in, not which mailing address it uses.
If no certificate exists, a licensed land surveyor can produce one. On an elevated house in an AE or VE zone the premium difference often pays for it inside a year or two, which is why we usually recommend it for an elevated home and usually do not for a slab house sitting low. And if your house is actually above the base flood elevation but the map still shows the lot in the floodplain, the certificate is also the input to FEMA’s Letter of Map Amendment process, which is the only clean way to get the designation corrected.
An elevation certificate can also tell you something you did not want to know. If the survey shows the lowest floor sits below base flood elevation, you now have a document that says so, and under the disclosure rules you cannot pretend you never saw it. That is the real risk, and it is the reason we talk this through before anyone orders one. For most elevated coastal homes the certificate helps, because the number it produces is better than FEMA’s estimate. For a low slab house in an AE zone it may simply confirm the premium, and the money is better spent elsewhere. The honest answer is that this is a judgment call on your specific house, not a rule, and anyone who tells you every seller should order one is not thinking about your house. Our Wilmington flood zone and flood insurance guide walks through the zones, and our post on what flood insurance actually costs at Wrightsville Beach shows how wide the spread inside one ZIP code can be.
Related questions people also ask
Can a buyer require an elevation certificate as a condition of the contract?
A buyer can ask for anything in an offer, and in coastal North Carolina they often do ask for a copy of any existing certificate. What they cannot do is force you to pay a surveyor for one unless you agree to it in the contract. If you do not have a certificate, the better move is usually to say so clearly up front rather than letting it surface during due diligence, when it reads as a surprise instead of a known fact.
Does an old elevation certificate still count?
Usually yes, as long as the building has not been altered in a way that changed its elevations and the certificate was completed by a qualified professional. Flood maps change more often than buildings do, so an older certificate can still describe the structure accurately even when the map around it has been revised. Give your insurance agent the certificate you have and let them tell you whether it still produces a usable rate.
Will an elevation certificate lower my own flood insurance while the house is listed?
It can, and under the National Flood Insurance Program the certificate will only be used if it produces a better rate than FEMA’s own elevation estimate. FEMA’s guidance says a policyholder may submit one to an agent to see whether it lowers the rate, and that if the lower rate applies after the policy has started, the premium is adjusted and a refund prorated back to the policy’s effective date. That makes it a reasonable thing to try even if your house does not sell this season.
Before you spend anything, call the floodplain administrator for the jurisdiction your house sits in and ask whether an elevation certificate is already on file for the address. That call is free and it answers the question for a large share of homes built in the last few decades. If nothing is on file, we will look at the house, the zone and the likely premium with you and tell you honestly whether a survey is worth it on your specific property. Our listing services page explains how we handle this before a coastal listing goes live, and the New Hanover County market update shows what you are selling into. Bring us the address and we will start with the phone call.
Sources: FEMA, Risk Rating 2.0 frequently asked questions and April 2025 Risk Rating 2.0 guidance, on elevation certificates no longer being required to purchase coverage and on submitting one to seek a lower rate, read October 13, 2026; FEMA Community Status Book, North Carolina, September 2026, Community Rating System classes and discounts; North Carolina Real Estate Commission rule 21 NCAC 58A .0114 and the Residential Property and Owners’ Association Disclosure Statement, rule record at the N.C. Office of Administrative Hearings, read October 13, 2026; New Hanover County Floodplain Development Permit Application and Article 9 of the Unified Development Ordinance, New Hanover County Planning and Land Use; Tidal Realty Partners New Hanover County market update, three months ending August 2026.



