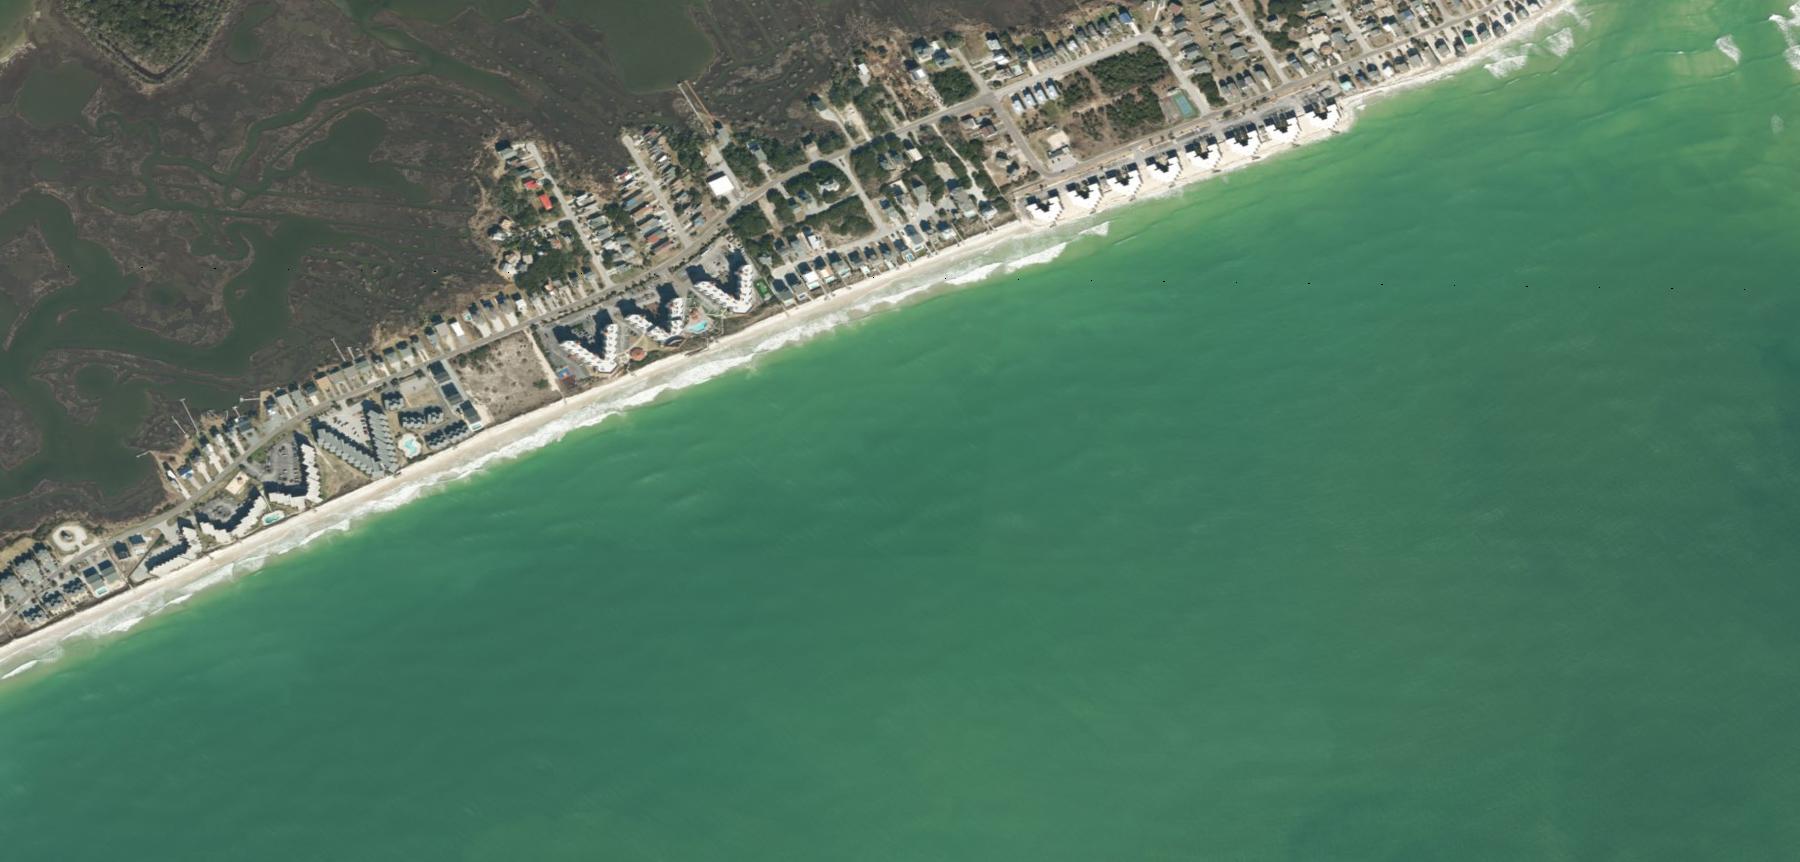
For most buyers, Surf City is the safer purchase and North Topsail Beach is the cheaper one, and the reason is insurance rather than scenery. A large part of North Topsail Beach sits inside the federal Coastal Barrier Resources System, where the National Flood Insurance Program cannot write a policy on a structure built or substantially improved after the area was designated.
That single rule drives more deals on Topsail Island than anything about views or beach access. It affects what you can insure, what a lender will accept, who can buy the house from you later, and what happens if the house is ever substantially damaged. Before you compare the two towns on price, you need to understand it.
Both towns are worth owning in. We have clients happy in each. But they are not the same risk, and the market has priced that difference in.
What the Coastal Barrier Resources Act actually does
Congress designated certain undeveloped coastal barriers in 1982 and withdrew most federal subsidies inside them, including flood insurance. Much of North Topsail Beach falls inside a designated unit. Surf City does not carry the same restriction across its developed areas.
FEMA states the rule plainly: the National Flood Insurance Program cannot provide coverage for structures built or substantially improved after an area was designated as part of the Coastal Barrier Resources System, with the original designations effective October 1, 1983. Buildings that were walled and roofed under a valid permit before that date can remain insurable, and that exception is why some North Topsail homes do carry federal policies.
The part that catches owners off guard comes later. If an insured building inside one of these units is substantially improved or substantially damaged, FEMA cancels the policy. A major renovation or a bad storm can end your coverage, not just raise your premium.
- North Topsail Beach area, ZIP 28460: median list price $439,000, 328 active listings, 128 days on market, $327 a square foot, 1,548 median square feet Realtor.com residential listings data, October 2026
- Surf City and Holly Ridge area, ZIP 28445: $639,400, 218 active listings, 78 days on market, $275 a square foot, 1,888 median square feet Realtor.com, October 2026
- Price cuts: 18.0 percent of listings in 28460, 19.4 percent in 28445 Realtor.com, October 2026
- Pender County median sale price $499,000 with 83 days on market and 430 active listings Tidal Realty Partners Pender County market update, September 2026 data
- Original Coastal Barrier Resources System designations effective October 1, 1983 FEMA, Coastal Barrier Resources System and NFIP Flood Insurance Manual Appendix D
Both ZIP codes include mainland as well as island property, so treat these as the shape of the two markets rather than the price of an oceanfront house. The useful signal is the direction: the North Topsail side is cheaper per house and more expensive per square foot, with 128 days on market against 78. That is a market telling you something about how long it takes to find the right buyer for a house with an insurance question attached to it.
What else separates the two towns
Surf City spans the Pender and Onslow county line and functions as the island’s town center, with a grocery store, restaurants, a hardware store and the high-rise bridge that replaced the old swing bridge. You can live there year round without planning your week around a drawbridge. North Topsail Beach is quieter and narrower, with fewer services and more rental-driven blocks.
Erosion is the other difference. The north end of the island has a long history of shoreline loss and sandbag revetments, and beach work inside a Coastal Barrier Resources System unit is not eligible for federal nourishment dollars. That shifts the cost onto the town and its property owners. Ask about assessments and the town’s beach management plan before you buy on that end.
Our Surf City guide and North Topsail Beach guide cover each town street by street, and our guide to buying a beach house near Wilmington walks through the rental income, insurance and management math on a coastal second home.
How to check a specific address before you make an offer
Do these four things in order, and do them during due diligence rather than after.
First, look up the address on the U.S. Fish and Wildlife Service CBRS Mapper, which is the official source for the boundaries. A listing remark is not evidence. Second, if the property is inside a unit, get a written quote from the private flood market before you remove your due diligence contingency, because the federal program will not be an option for most post-designation construction. Third, pull the FEMA flood map and the elevation certificate, since zone and elevation still drive what a private carrier charges. Fourth, ask your lender in writing whether it will lend on a private flood policy for that address. Some will not.
We cover flood zones and what each one means for your loan in our flood zone and flood insurance guide, and the wind and hurricane deductible side in our coastal homeowners insurance guide. You can also see how the county market is moving on our Pender County market update.
North Topsail Beach is not off limits, and we would not tell a cash buyer with an appetite for the risk to avoid it. Private flood carriers do write on the island, the pricing is sometimes competitive, and the lower purchase price is real. What we will not do is let a buyer assume a federal policy is available because the seller has one. The seller’s policy may be tied to a pre-1983 building that has never been substantially improved, and that status does not transfer to your renovation plans. Boundaries also change. The Fish and Wildlife Service has revised this unit before, in both directions, so check the current map rather than an old survey.
Related questions people also ask
Can you get a mortgage on a home in a Coastal Barrier Resources System unit?
Often yes, but not always, and it depends on the lender rather than the property. A lender still needs flood coverage in a special flood hazard area, and if the federal program cannot write the policy, the lender has to accept a private flood policy instead. Many lenders do. Some, particularly smaller portfolio lenders and certain government loan programs, will not. Confirm your lender’s position in writing before you go under contract.
Is private flood insurance more expensive than a federal policy?
Sometimes, and sometimes less. Private carriers price on their own models and can be cheaper on a house that sits high above the base flood elevation, while a lower or older structure may cost considerably more or be declined. The difference from the federal program is that private carriers can change appetite or raise pricing at renewal in ways the federal program cannot, so plan for less predictability over a long hold.
Is Surf City in Pender County or Onslow County?
Both. The town straddles the county line, with part of it in Pender County and part in Onslow County, which means your tax bill, your school assignment and your county services depend on which side of the line the property sits on. Buyers are frequently surprised by this, so confirm the county for the specific address before you compare tax figures between two listings in the same town.
Send us the addresses you are considering on either end of the island. We will check each one against the official Coastal Barrier Resources System map, tell you what insurance path it has, and show you the comparable sales behind the asking price so you can see whether the discount on the north end is actually worth taking. It is a short conversation that saves a long one later.
Sources: FEMA, Coastal Barrier Resources System page and NFIP Flood Insurance Manual Appendix D, April 2021; U.S. Fish and Wildlife Service CBRS Mapper, the official boundary source; Town of North Topsail Beach and Coastal Review reporting on Coastal Barrier Resources Act coverage of the town; Realtor.com residential listings data by ZIP code, October 2026; Tidal Realty Partners Pender County market update, September 2026 data.