Right now the money is on the spec home. The largest incentives our builders are publishing this month are tied to specific inventory homes and to hard closing deadlines, which a to-be-built house usually cannot meet, so choosing build to order often means paying today’s rate instead of a buydown.
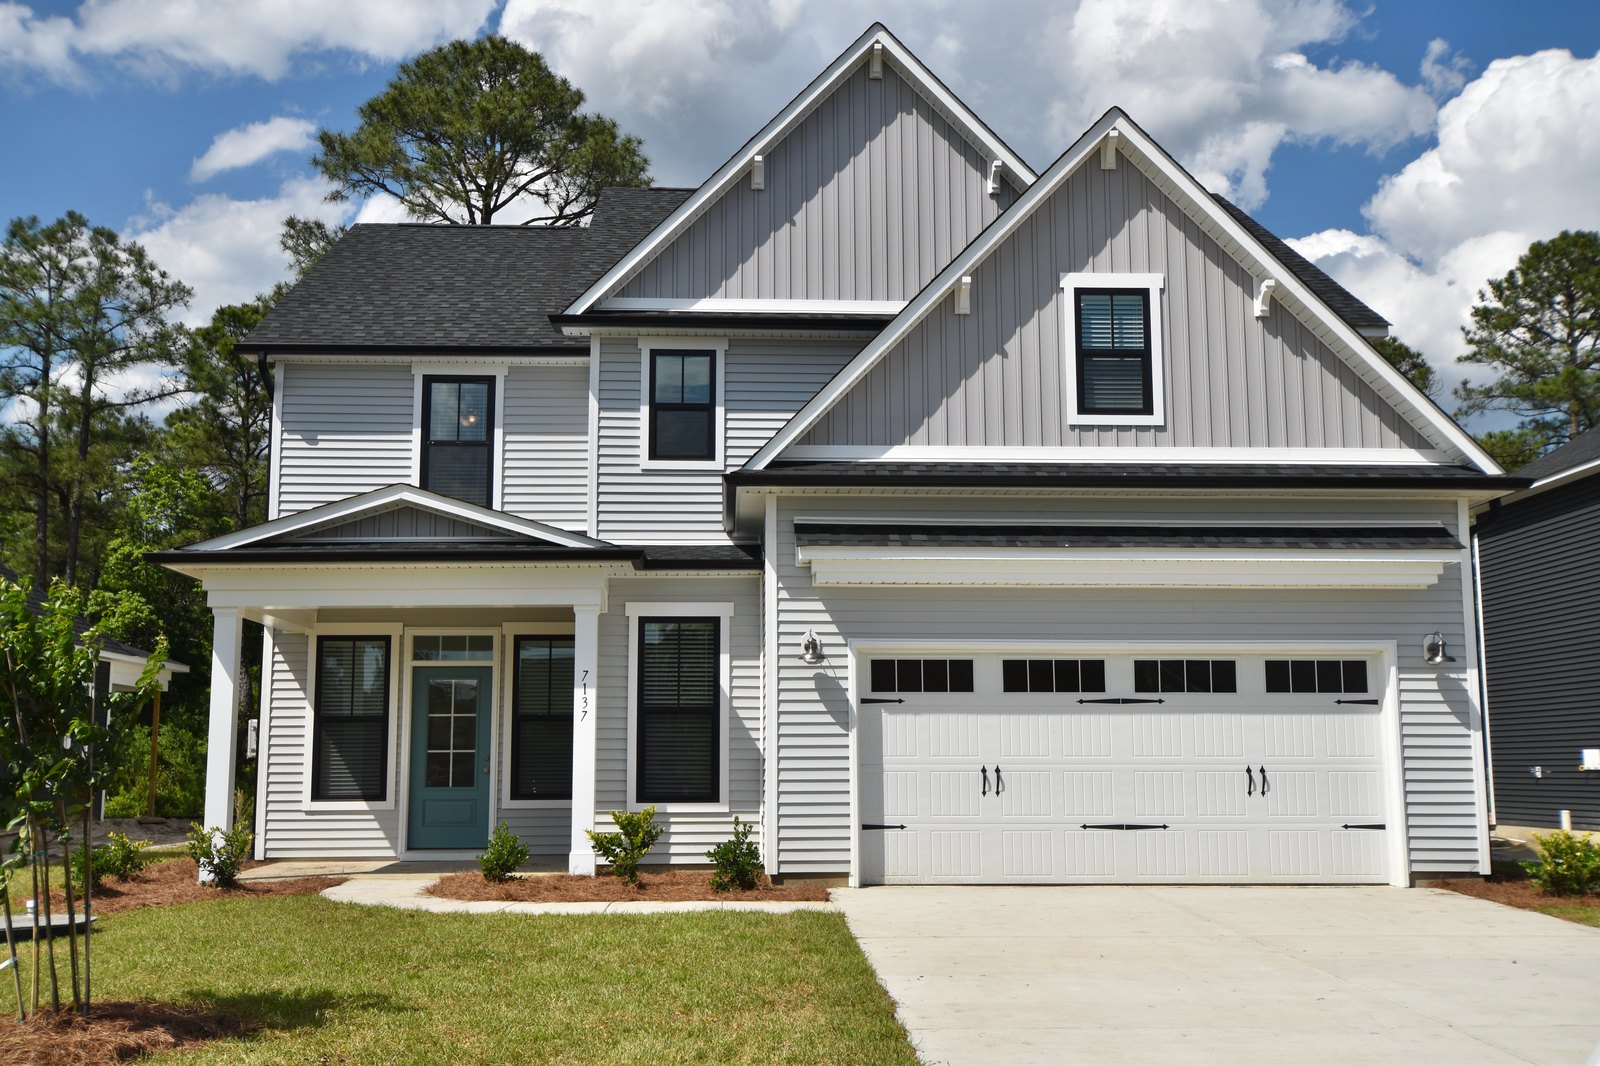
A spec home, which builders also call an inventory home or a quick move-in, is a house the builder started without a buyer under contract. Build to order means you pick the lot, the plan and the finishes, and the builder starts after you sign. Most buyers assume the second one costs more because you are choosing. In this market the gap is not really about the finishes. It is about financing.
Here is the arithmetic, using what the builders we work with are actually publishing this month.
Where the money is right now
Mungo Homes is publishing a 2/1 buydown at 3.49 percent in year one, 4.49 percent in year two and 5.49 percent for years three through thirty, at 6.237 percent APR, through Silverton Mortgage. The published terms apply to eligible homes, for contracts written on or after September 14, 2026, with the loan required to close before January 12, 2027, and the rates holding only until the locked pool of funds is depleted. The alternative is up to $20,000 in savings with the same lender, and eligible homes are set by the builder’s sales manager (Tidal Realty Partners Mungo Homes page, builder published materials as of October 19, 2026).
Logan Homes is publishing $20,000 use-as-you-choose on select homes in select communities for contracts written October 1 to 31, 2026, and a first-time buyer package with a rate as low as 5.75 percent or up to $5,000 toward buyer fees plus a washer, dryer, refrigerator and blinds on select homes, with that package requiring the home to close no later than December 31, 2026. Both require financing with Alpha Mortgage and closing with Cline Law (Tidal Realty Partners Logan Homes page, builder published materials as of October 19, 2026). HHHunt’s current published offer is a $1,500 Hometown Heroes credit rather than a rate buydown (Tidal Realty Partners mortgage update, terms as of October 17, 2026).
Read the conditions, not the headline. Select homes. Eligible homes. Close before January 12. Close no later than December 31. Those four phrases are the answer to this whole question. A house that has not been started cannot close by December 31, so the first-time buyer rate is a spec-home offer whether or not the flyer says so.
- Mungo Homes: 104 new homes for sale across its seven Wilmington-area communities Builder published materials as of October 19, 2026
- Inventory by community: 20 homes at Scotts Hill Village, 19 at Avenue One with five under construction, 14 at River Tide Farms, 10 at Indigo at Abbey Preserve, 8 at East Wynd, 3 at Citadel Point at Southbridge Builder published materials as of October 19, 2026
- Mungo 2/1 buydown: 3.49 percent year one, 4.49 percent year two, 5.49 percent thereafter, 6.237 percent APR, on eligible homes, loan must close before January 12, 2027 Builder published materials as of October 19, 2026
- On a $400,000 home, the published Mungo buydown costs the seller about $8,500 Tidal Realty Partners Mungo Homes page, October 19, 2026
- 30-year fixed mortgage average: 7.32 percent Freddie Mac Primary Mortgage Market Survey, October 22, 2026
The spread is the point. The 30-year averaged 7.32 percent on October 22, 2026, and the published first-year rate on an eligible Mungo home is 3.49 percent. Nothing you choose at a design center is worth that difference in the first two years of a payment.
What build to order actually buys you
We are not telling you to take whatever is standing. Build to order buys three real things, and for some buyers each one is worth more than a buydown.
The lot. In most of these communities the specs are on the homesites that did not sell first, which often means the interior lots rather than the ones backing to trees, water or the preserve. If you have walked a community and know which lot you want, that is a permanent advantage and the spec inventory cannot give it to you.
The plan. Mungo publishes 10 floor plans at East Wynd, 14 at Indigo at Abbey Preserve and 12 at Avenue One, and Grand Park spans 1,693 to 4,336 square feet. Logan’s Turtle Creek in Surf City has three villages and 16 plans from 1,243 to 2,249 square feet (builder published materials as of October 19, 2026). With that many plans, the specific one you need is often not the one sitting finished.
The finishes. Paying for your own choices up front is usually cheaper than changing them after closing, and it is the one part of the house a later renovation cannot easily fix, like the kitchen layout or where the laundry goes.
The rate risk is the real difference
When you buy a spec home you are close enough to closing that your lock covers the whole timeline. When you build to order you are nine months to a year out, and nobody can lock a rate that far ahead on standard terms. That means you take the rate risk between signing and delivery.
That is not hypothetical. The 30-year rose from 6.66 percent in late August to 7.40 percent by October 15, 2026, which is 74 basis points in eight weeks and the highest reading since November 2023, before easing to 7.32 percent the following week (Tidal Realty Partners mortgage update, week ending October 15, 2026; Freddie Mac Primary Mortgage Market Survey, October 22, 2026). A buyer who signed a build-to-order contract in late August and is closing in the spring has already watched their payment estimate move. We walk through how we think about that in our post on whether to lock a rate above 7 percent, and the broader trade between new and resale is in our new construction versus resale comparison.
There is a market reason this favors buyers either way. Brunswick County had 2,334 active listings and a 93-day median, and New Hanover had 1,251 active listings and 61 days, with two of every five New Hanover listings having already taken a price cut (Tidal Realty Partners market updates, September 2026 data). Builders feel that. It is why the incentives are this large, and it is why asking for something is reasonable.
Every one of these incentives is tied to the builder’s lender, and some to the builder’s closing attorney, so the headline number is not what you save. A rate the builder’s lender offers can come with pricing elsewhere in the loan, and the only way to know is to put a competing quote next to it, which is what we do for our buyers before they sign. The buydown versus credit choice also depends on how long you keep the loan: Mungo’s published buydown costs about $8,500 on a $400,000 home and front-loads your savings into two years, while the $20,000 credit is worth more if you hold the loan long enough. Neither is automatically right. And a spec home that has sat for months is worth asking about, because the reason it sat is sometimes the lot, sometimes the plan, and sometimes nothing at all. We would rather tell you which one it is than talk you into the incentive. If the lot you want is not available as a spec, build to order and plan the rate risk on purpose. Our new construction guide covers the questions to ask before your first visit, and registration on that first visit is the one step that cannot be undone.
Related questions people also ask
What is a spec home?
A spec home is a house a builder starts without a buyer under contract, choosing the plan, the lot and the finishes itself. Builders also call them inventory homes or quick move-ins, and they range from a slab just poured to a finished house with a model-home upgrade package. Because the builder is carrying the cost until it sells, a spec home is usually where the strongest incentives sit.
Can I negotiate on a spec home that has been sitting?
Often yes, though builders in this market generally protect the published price and negotiate through incentives instead, because a recorded price cut affects every other home in the community. That means the realistic ask is a larger closing credit, a rate buydown, or upgrades rather than a lower number on the contract. Ask how long the home has been complete, because a builder’s willingness changes once a finished house has been carried for a few months.
Do builder incentives apply to build-to-order homes?
Sometimes, but usually at a lower level, and the biggest offers this month are restricted to specific eligible or select homes and to loans that close by a stated date. A to-be-built home that delivers next spring cannot meet a December or January closing deadline, so it generally cannot claim those offers. Always ask the builder in writing which homes qualify and what the incentive is worth on a to-be-built contract before you choose a path.
Pick one community you are serious about and ask for two written quotes on the same floor plan: one on an eligible spec home with the current incentive, and one on a to-be-built home with your lot. Then put a competing lender quote next to the builder’s. Schedule a consultation and our team will pull the current inventory and incentive terms for you, register you before your first visit so you keep representation, and tell you which of the two actually costs less.
Sources: Tidal Realty Partners Mungo Homes and Logan Homes pages, builder published materials as of October 19, 2026. Tidal Realty Partners monthly mortgage update, builder incentive terms as of October 17, 2026 and Freddie Mac week ending October 15, 2026. Freddie Mac Primary Mortgage Market Survey, October 22, 2026. Tidal Realty Partners New Hanover County and Brunswick County market updates, September 2026 data.