If you know your house has flooded, the state’s disclosure form asks you about it directly, and answering Yes means you also have to explain it in writing. You can answer No Representation instead, which is legal on these questions, but it is visible to every buyer who reads the form and your broker still has to disclose material facts they know about the property regardless of what you check.
North Carolina law, N.C.G.S. 47E, requires residential property owners to complete the Residential Property and Owners’ Association Disclosure Statement and give it to the buyer no later than the time the buyer makes an offer. If you do not, the buyer can, under certain conditions, cancel any resulting contract. The current form is the North Carolina Real Estate Commission’s form REC 4.22, revision 7/26, and it runs six pages, with a whole section on flooding.
That section is newer than most sellers realize, and it is the reason this question comes up on nearly every listing we take near a creek, a sound or the Cape Fear. The old form asked one flood question. The current one asks six.
What does the form actually ask about flooding?
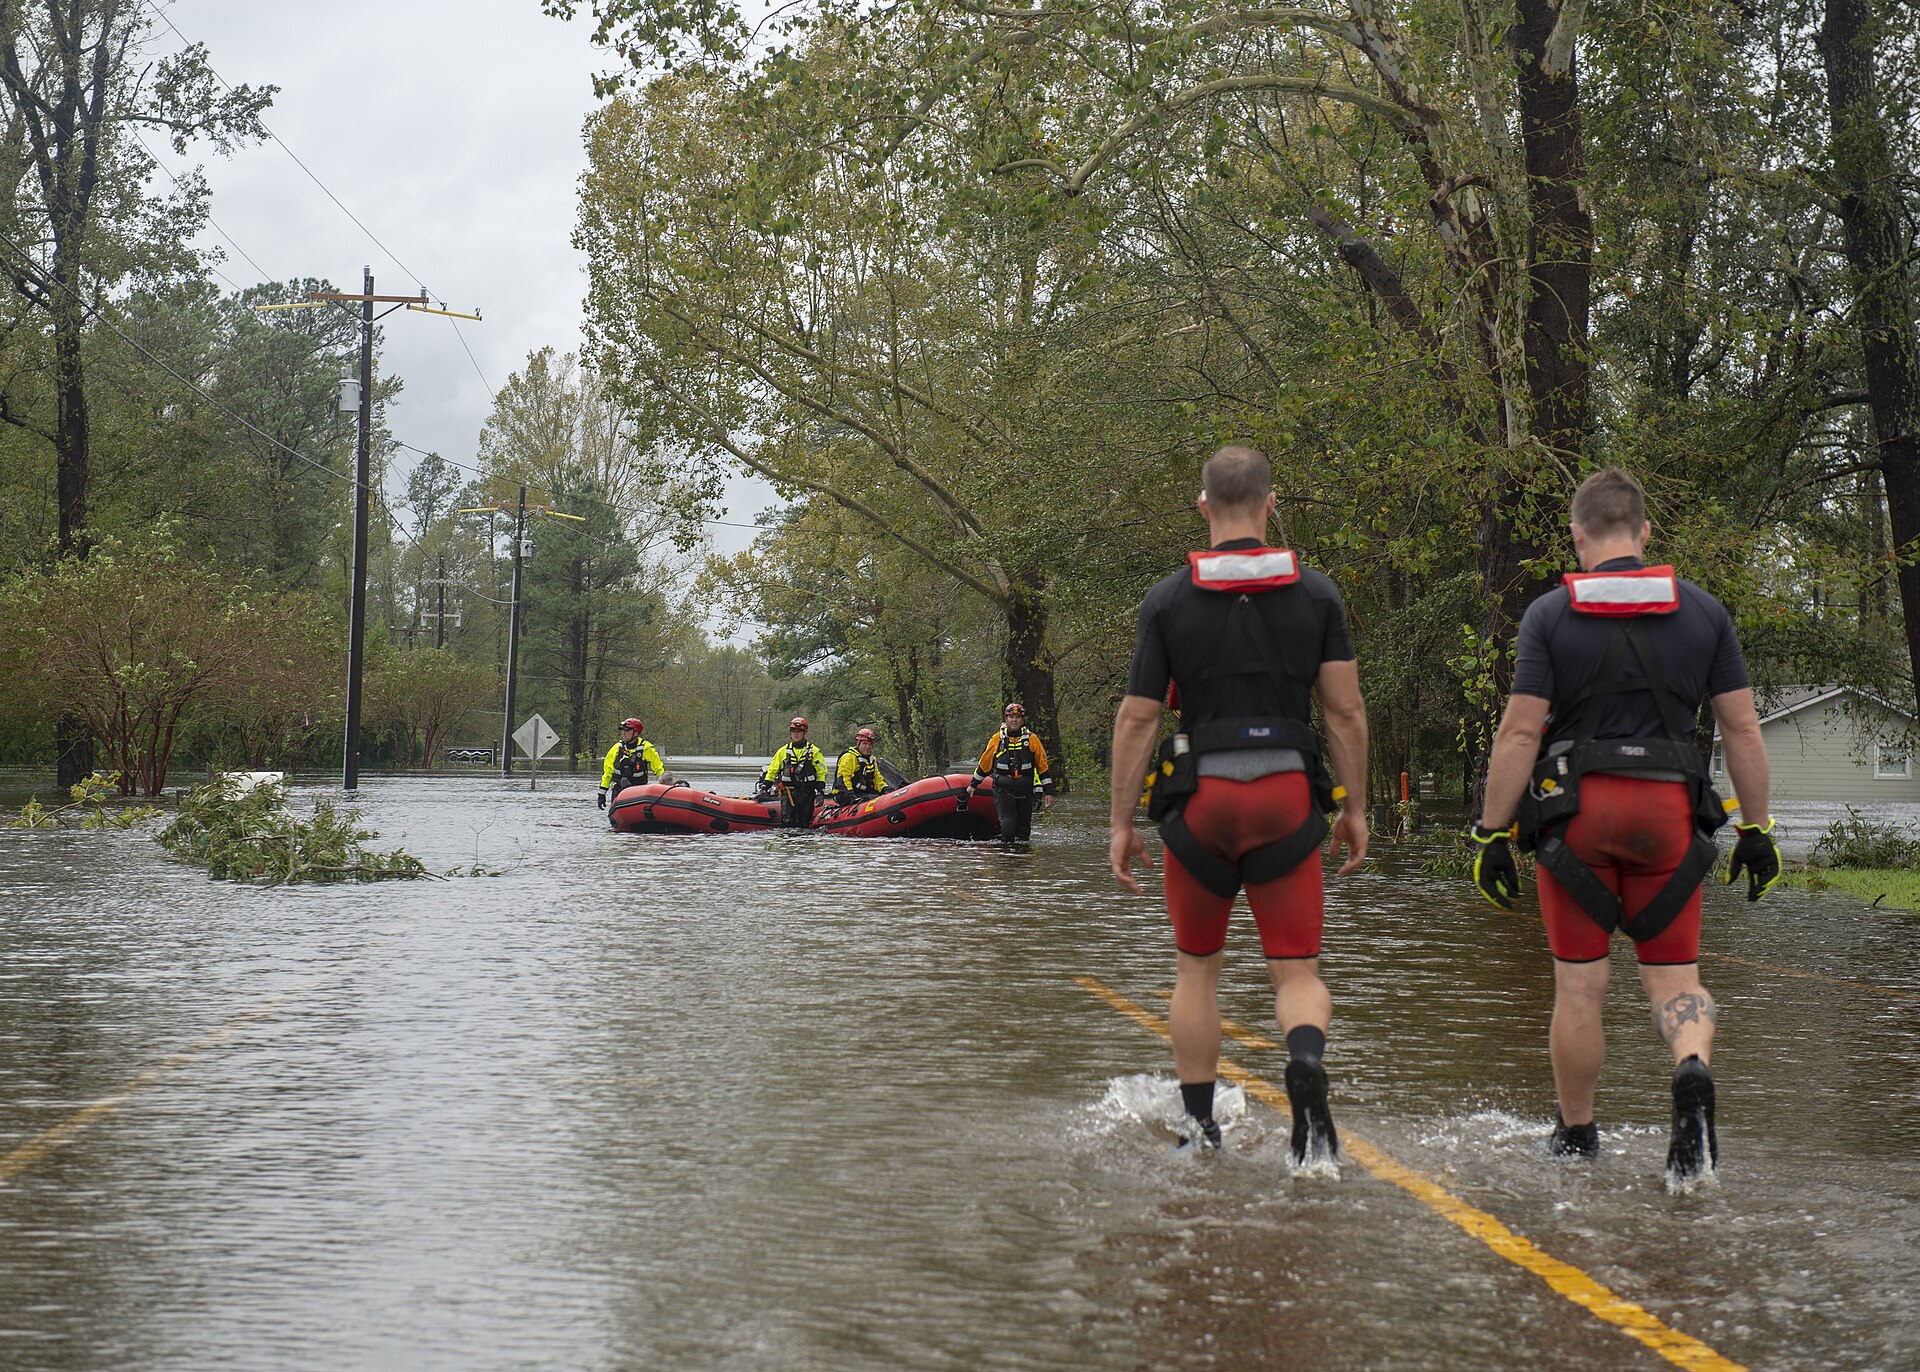
Section F, Environmental and Flooding, carries six separate flood items, and each one gets a Yes, No, No Representation or Not Applicable answer. F5 asks whether the property is located in a federal or other designated flood hazard zone. F6 asks whether the property has experienced damage due to flooding, water seepage, or pooled water attributable to a natural event such as heavy rainfall, coastal storm surge, tidal inundation, or river overflow. F7 asks whether you have ever filed a claim for flood damage to the property with any insurance provider, including the National Flood Insurance Program. F8 asks whether there is a current flood insurance policy on the property. F9 asks whether you have received assistance from FEMA, the Small Business Administration, or any other federal disaster flood assistance for flood damage. F10 asks whether there is a flood or FEMA elevation certificate for the property.
Read F6 and F7 together, because that pairing is what catches people. A seller who had two inches of water in a garage after a tropical system and paid for the drywall themselves sometimes assumes there is nothing to report because there was no claim. F6 is not a claims question. It asks about the damage, however it was paid for.
The form also sets the rules for what your answers mean. If you select Yes to any question about a problem, you must provide a written explanation or attach a report from an attorney, engineer, contractor or public agency describing it. If you select No, you are saying you have no actual knowledge of the topic, and if you know the answer is not correct, the form warns you may be liable for making an intentional misstatement. An owner is not required to disclose material facts that have a No Representation option, even with knowledge of them, but the form is equally clear that failure to disclose latent, hidden defects may result in civil liability.
So can you just mark No Representation and move on?
You can, and some sellers should. An estate executor who never lived in the house, or an owner who bought four years ago and genuinely does not know what happened in 2018, is answering honestly with No Representation. That is what the option is for.
The mistake we see just as often is the seller who checks No Representation down the whole flooding section as a shield. It does not work the way they expect. The form tells buyers in plain language that No Representation could mean the owner has knowledge of an issue and chooses not to disclose it, or simply does not know, and buyers read it that way. On a property where the flood zone itself is a matter of public record, a blank next to F5 reads as evasion rather than caution, and it tends to produce more inspections, a flood determination ordered on day one and a buyer looking for a reason to renegotiate.
There is also the part sellers forget: your broker’s duty is separate from yours. The form states that all brokers shall take reasonable steps to disclose material facts about the property that the broker knows or reasonably should know, regardless of the owner’s responses or representations, and that brokers are not permitted to complete the disclosure statement on behalf of their seller-clients. If we know your house took water in Florence, we are disclosing that whether the form says Yes or No Representation. We tell sellers that at the listing appointment, not after an offer.
- Six separate flooding questions in Section F of the current disclosure form, F5 through F10, on a six-page form NC Real Estate Commission form REC 4.22, revision 7/26
- Delivery deadline: no later than the time the buyer makes an offer, or the buyer may be able to cancel the resulting contract N.C.G.S. 47E, as stated on form REC 4.22
- Median days on market: 61 in New Hanover, 83 in Pender, 93 in Brunswick, against about four to five weeks faster a year ago Our county market updates, three months ending September 2026
- Median annual NFIP policy cost inside the Town of Shallotte: $528 outside the mapped hazard area, $1,285 in Zone A or AE FEMA OpenFEMA NFIP policy data, policies effective on or after September 1, 2025, retrieved October 15, 2026
That days-on-market line matters more than it looks. With a median of two to three months to sell across our three counties, as our New Hanover County market update lays out, buyers are not making snap decisions, and a disclosure problem discovered in week six of due diligence costs you the week-one buyer pool you already spent.
Two things on the form that can work in your favor
The flood section is not purely a liability. The form’s own note points out that an existing flood insurance policy may be assignable to a buyer at a lesser premium than a new policy. If you have held an older National Flood Insurance Program policy, that assignment can be worth real money to your buyer, and it is a reason to answer F8 with a confident Yes and have the declarations page ready.
F10, the elevation certificate question, works the same way. An elevation certificate showing the lowest floor above the base flood elevation is the document that prices a buyer’s policy, and in our experience a listing in an AE zone that hands over a current certificate holds its price better than one that makes the buyer go find out. Our Wilmington flood zone and flood insurance guide explains what the certificate changes and what it costs to get one.
The one place to be careful is F9. The form states that for properties that have received disaster assistance, the requirement to obtain flood insurance passes down to all future owners, and that failure to obtain it can make an owner ineligible for future assistance. That is not a disclosure you can quietly skip, because it follows the property rather than you.
Repairs do not erase a material fact. The form notes that some issues, even if repaired, such as structural issues and fire damage, remain material facts and must be disclosed by a broker after the repair is done. Flood damage that was properly remediated often falls in the same category in practice, which means the honest play is usually to disclose it with the invoices and the scope of work attached rather than to leave a blank and let a buyer’s inspector find a tide line in the crawl space. The second complication is timing: if something changes after you deliver the form, for example the roof starts to leak or you file a claim, you must promptly give the buyer an updated disclosure statement or correct the problem. And none of this is legal advice. If your situation involves a claim, a disaster grant or an insurance dispute, talk to a North Carolina real estate attorney before you fill in the form, because the exemptions in N.C.G.S. 47E-2 are narrow and the consequences are yours.
Related questions people also ask
Can I answer No Representation on the flood questions in North Carolina?
Yes. The North Carolina disclosure form gives owners a No Representation option on these items, and the form states that an owner is not required to disclose material facts that carry that option even if they have knowledge of them. The form also tells buyers that No Representation could mean the owner knows about an issue and chose not to disclose it, so the answer is visible and it is read that way. Separately, the owner’s broker must still disclose material facts the broker knows or reasonably should know, regardless of what the owner checked.
Does the North Carolina disclosure form ask about flood insurance claims?
It does, directly. Question F7 on form REC 4.22 asks whether the owner has ever filed a claim for flood damage to the property with any insurance provider, including the National Flood Insurance Program, and F9 asks whether the owner has received assistance from FEMA, the Small Business Administration or any other federal disaster flood assistance. Those are two different questions and a property can trigger one without the other. If a property received disaster assistance, the form states the requirement to obtain flood insurance passes down to all future owners.
When do I have to give a buyer the disclosure statement in NC?
No later than the time the buyer makes an offer to purchase the property, under N.C.G.S. 47E as stated on the form. If the owner does not deliver it by then, the buyer can, under certain conditions, cancel any resulting contract. There are limited exemptions, such as new construction that has never been occupied, and the Commission advises owners who believe an exemption applies to seek legal advice. The practical approach is to complete it before the listing goes live so it is attached from day one rather than chased during negotiation.
Before you sign the form, pull what you actually have: your insurance claim history, any FEMA or Small Business Administration assistance letters, the invoices from any water remediation, and the elevation certificate if one exists. Then sit down with your broker and answer the six questions with the documents in front of you rather than from memory. If you want help deciding how to present a flood history without losing the buyer pool, talk it through with our team.
Sources: North Carolina Real Estate Commission, Residential Property and Owners’ Association Disclosure Statement, form REC 4.22, revision 7/26, read October 19, 2026, including Section F questions F5 through F10 and the owner, buyer and broker instructions. N.C.G.S. 47E and 47E-2, as cited on the form. Our New Hanover County, Pender County and Brunswick County market updates, three months ending September 2026. FEMA OpenFEMA NFIP policy data, single-family policies effective on or after September 1, 2025, Town of Shallotte, retrieved October 15, 2026.