
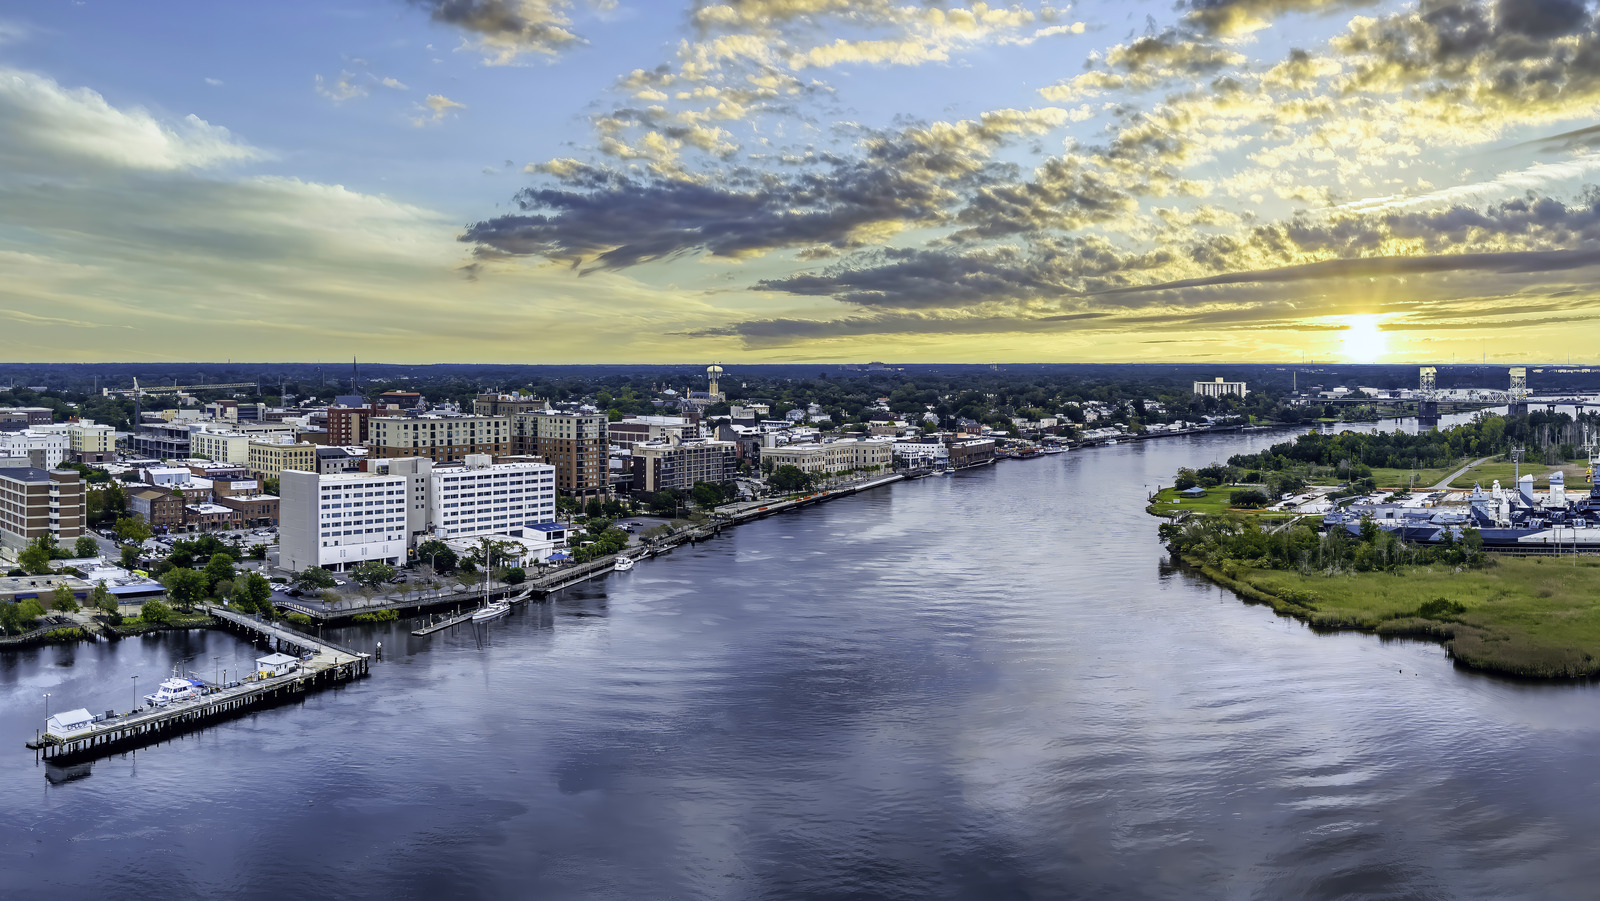
No, a downtown Wilmington condo is not a bad idea, but it is a different purchase from a downtown house and it goes wrong in three specific places: the association’s reserves, your lender’s review of the building, and a flood line that runs between Front Street and Second Street. Get all three right and downtown is one of the few places in this region where you can genuinely live with one car.
We hear the worry in two forms. Buyers relocating here ask whether a condo will hold its value in a city where almost everyone buys a house. Buyers already in Wilmington ask whether they are walking into someone else’s deferred maintenance. Both are fair, and both come down to documents rather than to the building’s charm.
Here is what we check before we let a client get attached to a downtown unit.
Does the flood zone actually matter downtown?
It matters more than almost anything else, and it changes within two blocks. We queried FEMA’s National Flood Hazard Layer at four downtown points on October 2, 2026. Water Street at Market Street came back Zone AE with a base flood elevation of 9 feet. The Front Street block at Market came back Zone AE at 9 feet as well. South Second Street at Market came back Zone X, an area of minimal flood hazard, and so did South Third Street at Market.
That is the whole story in one paragraph. A riverfront or Front Street building sits in a special flood hazard area, which means flood insurance is required on a federally backed mortgage. Walk a couple of blocks east and the requirement goes away. Two units with the same view of the same church steeple can carry very different monthly costs.
Flood coverage on a condo also works differently than on a house. The National Flood Insurance Program writes the building through the association’s Residential Condominium Building Association Policy, with a building limit of $250,000 multiplied by the number of units, while your own NFIP contents coverage is capped at $100,000. In practical terms, in Zone AE you are relying on the association’s flood policy to rebuild the structure. Ask for the declarations page, not a summary. Our complete guide to Wilmington flood zones and flood insurance covers how elevation certificates and zone determinations work across the region.
What should you read in the HOA documents?
Two numbers in the association’s budget decide whether your lender will finance the unit at all, and most buyers never see them until it is late.
Under Fannie Mae’s full project review standards, a condo project must fund replacement reserves at a minimum of 10% of its annual budget, and no more than 15% of total units may be 60 or more days past due on common expense assessments or on any special assessment. A building that fails either test can fall out of conventional eligibility. That does not just raise your cost. It shrinks the pool of buyers who can finance a unit in that building when you go to sell, which is the quiet way a condo loses value while the neighborhood around it gains.
So ask for the budget, the reserve study if one exists, the last two years of meeting minutes, and the current delinquency rate. Minutes are the most useful document in the stack. A roof discussion that has been tabled three times is a special assessment that has not happened yet.
- Water Street and the Front Street block at Market Street: FEMA Zone AE, base flood elevation 9 feet. South Second and South Third at Market: Zone X FEMA National Flood Hazard Layer, queried October 2, 2026
- NFIP condominium building coverage: $250,000 per unit through the association’s policy; unit owner contents capped at $100,000 FEMA, National Flood Insurance Program condominium coverage rules
- Lender threshold: replacement reserves of at least 10% of the association budget, and no more than 15% of units 60-plus days delinquent Fannie Mae Selling Guide B4-2.2-02
- Combined tax rate inside the downtown Municipal Service District: 68.75 cents per $100, county 30.6 plus city 33.15 plus MSD 5 Port City Daily, July 2026
- Historic Downtown median home price about $615,000, with condos from around $300,000, at about 60 average days on market Tidal Realty Partners Historic Downtown guide, 2026
What does a downtown condo cost to carry?
Property tax downtown carries a surcharge most buyers do not know about. The City of Wilmington operates a Municipal Service District covering a 70-block section of the central business district, managed by Wilmington Downtown, Inc., which funds extra cleaning, ambassadors, beautification and marketing, according to the city’s Municipal Services District page read October 2, 2026. Properties inside it pay the district rate on top of the county and city rates. For fiscal 2026-2027 that stack is 30.6 cents for New Hanover County, 33.15 cents for the City of Wilmington and 5 cents for the district, a combined 68.75 cents per $100, according to Port City Daily’s July 2026 reporting.
On a $450,000 condo inside the district that is about $3,094 a year, against about $2,869 for the same value just outside it. Worth noting: the city’s own Municipal Services District page still describes the district rate as 7 cents, so check the rate printed on the actual parcel rather than trusting either number in the abstract. Either way, add dues on top, and dues downtown vary so widely building to building that we will not quote you an average.
For context on the wider market, New Hanover County’s median sale price was $448,000 over the three months ending August 2026, down 3.5% year over year, with 58 days on market and active listings up 10.2%, per Redfin figures in our New Hanover County market update. Downtown condos trade in a thinner market than detached houses, which cuts both ways: fewer competing listings when you buy, fewer ready buyers when you sell. Our Historic Downtown community guide covers the district itself, from the Riverwalk to the schools.
What about renovations and rentals?
Downtown Wilmington is a 230-block National Register historic district, per our Historic Downtown community guide, and exterior work on contributing structures goes through review. For a condo this matters less than for a house, because the exterior is usually the association’s responsibility rather than yours, but it shapes how long and how expensively the building can fix its own facade and windows. We went through the mechanics in buying a historic home in downtown Wilmington.
On rentals, read the condominium declaration and the association rules before you count on any rental income, short or long term. A building’s own restriction binds you regardless of what the city permits, and plenty of declarations cap rentals, require a minimum lease term or set a waiting period for new owners. If a short-term rental is central to your plan, verify it in the recorded documents first. Our piece on running a short-term rental in Carolina Beach shows how much the local layer varies inside one county.
A downtown condo is a bad idea for one specific buyer: the person who needs to sell in three years. It is a thinner resale market than Ogden or Leland, your buyer pool depends on a building you do not control staying financeable, and a special assessment you did not vote for can arrive in year two. If your horizon is short, a townhome in a newer association with a funded reserve study is usually the safer version of the same lifestyle. The second honest point is that we cannot generalize about downtown. The buildings here range from 1800s conversions to riverfront construction, and the difference between a well-run association with real reserves and a poorly run one is larger than the difference between any two neighborhoods in this city. The analysis has to be done on one building, not on downtown.
Related questions people also ask
Do downtown Wilmington condos hold their value?
Some do and some do not, and the deciding factor is usually the association rather than the location. A building with funded reserves, a current reserve study and no history of surprise assessments stays financeable, which keeps the buyer pool wide and supports value. A building with thin reserves and deferred maintenance can lose conventional financing eligibility, and once buyers have to pay cash or use a portfolio loan, prices soften even while the neighborhood around the building improves.
Is flood insurance required for a condo in downtown Wilmington?
It depends on the building’s flood zone, not on the fact that it is a condo. If the structure sits in a FEMA special flood hazard area, flood insurance is required when you finance with a federally backed mortgage, and the coverage on the building itself typically comes through the association’s policy rather than your own. Buildings a couple of blocks inland from the river are often mapped outside those zones, so the requirement can differ between two units in the same neighborhood.
What is a special assessment, and can the HOA make me pay it?
A special assessment is a one-time charge the association levies on owners for a cost the regular budget and reserves cannot cover, most often a roof, elevator, facade or structural repair. Yes, the association can require you to pay it, under the authority in the recorded declaration and the state condominium statutes, and it binds you as a current owner even if the work was deferred for years before you bought. This is why the meeting minutes and the reserve balance matter more than the finishes in the unit.
Before you write an offer on any downtown unit, ask the listing agent for four documents: the association budget, the last two years of board minutes, the master insurance declarations page, and the current delinquency rate. If any of the four is slow to arrive, treat that as information. Send us the building and we will pull the FEMA flood zone, the tax card and the recorded declaration, read the documents with you, and tell you honestly whether that building is the one to buy in.
Sources: FEMA National Flood Hazard Layer, queried October 2, 2026. FEMA, National Flood Insurance Program condominium coverage limits. Fannie Mae Selling Guide B4-2.2-02, full review process. Port City Daily, New Hanover County fiscal 2026-2027 tax rates, July 10, 2026. City of Wilmington, Municipal Services District page, read October 2, 2026. Redfin, New Hanover County median sale price, three months ending August 2026, via our New Hanover County market update. Tidal Realty Partners Historic Downtown community guide.



