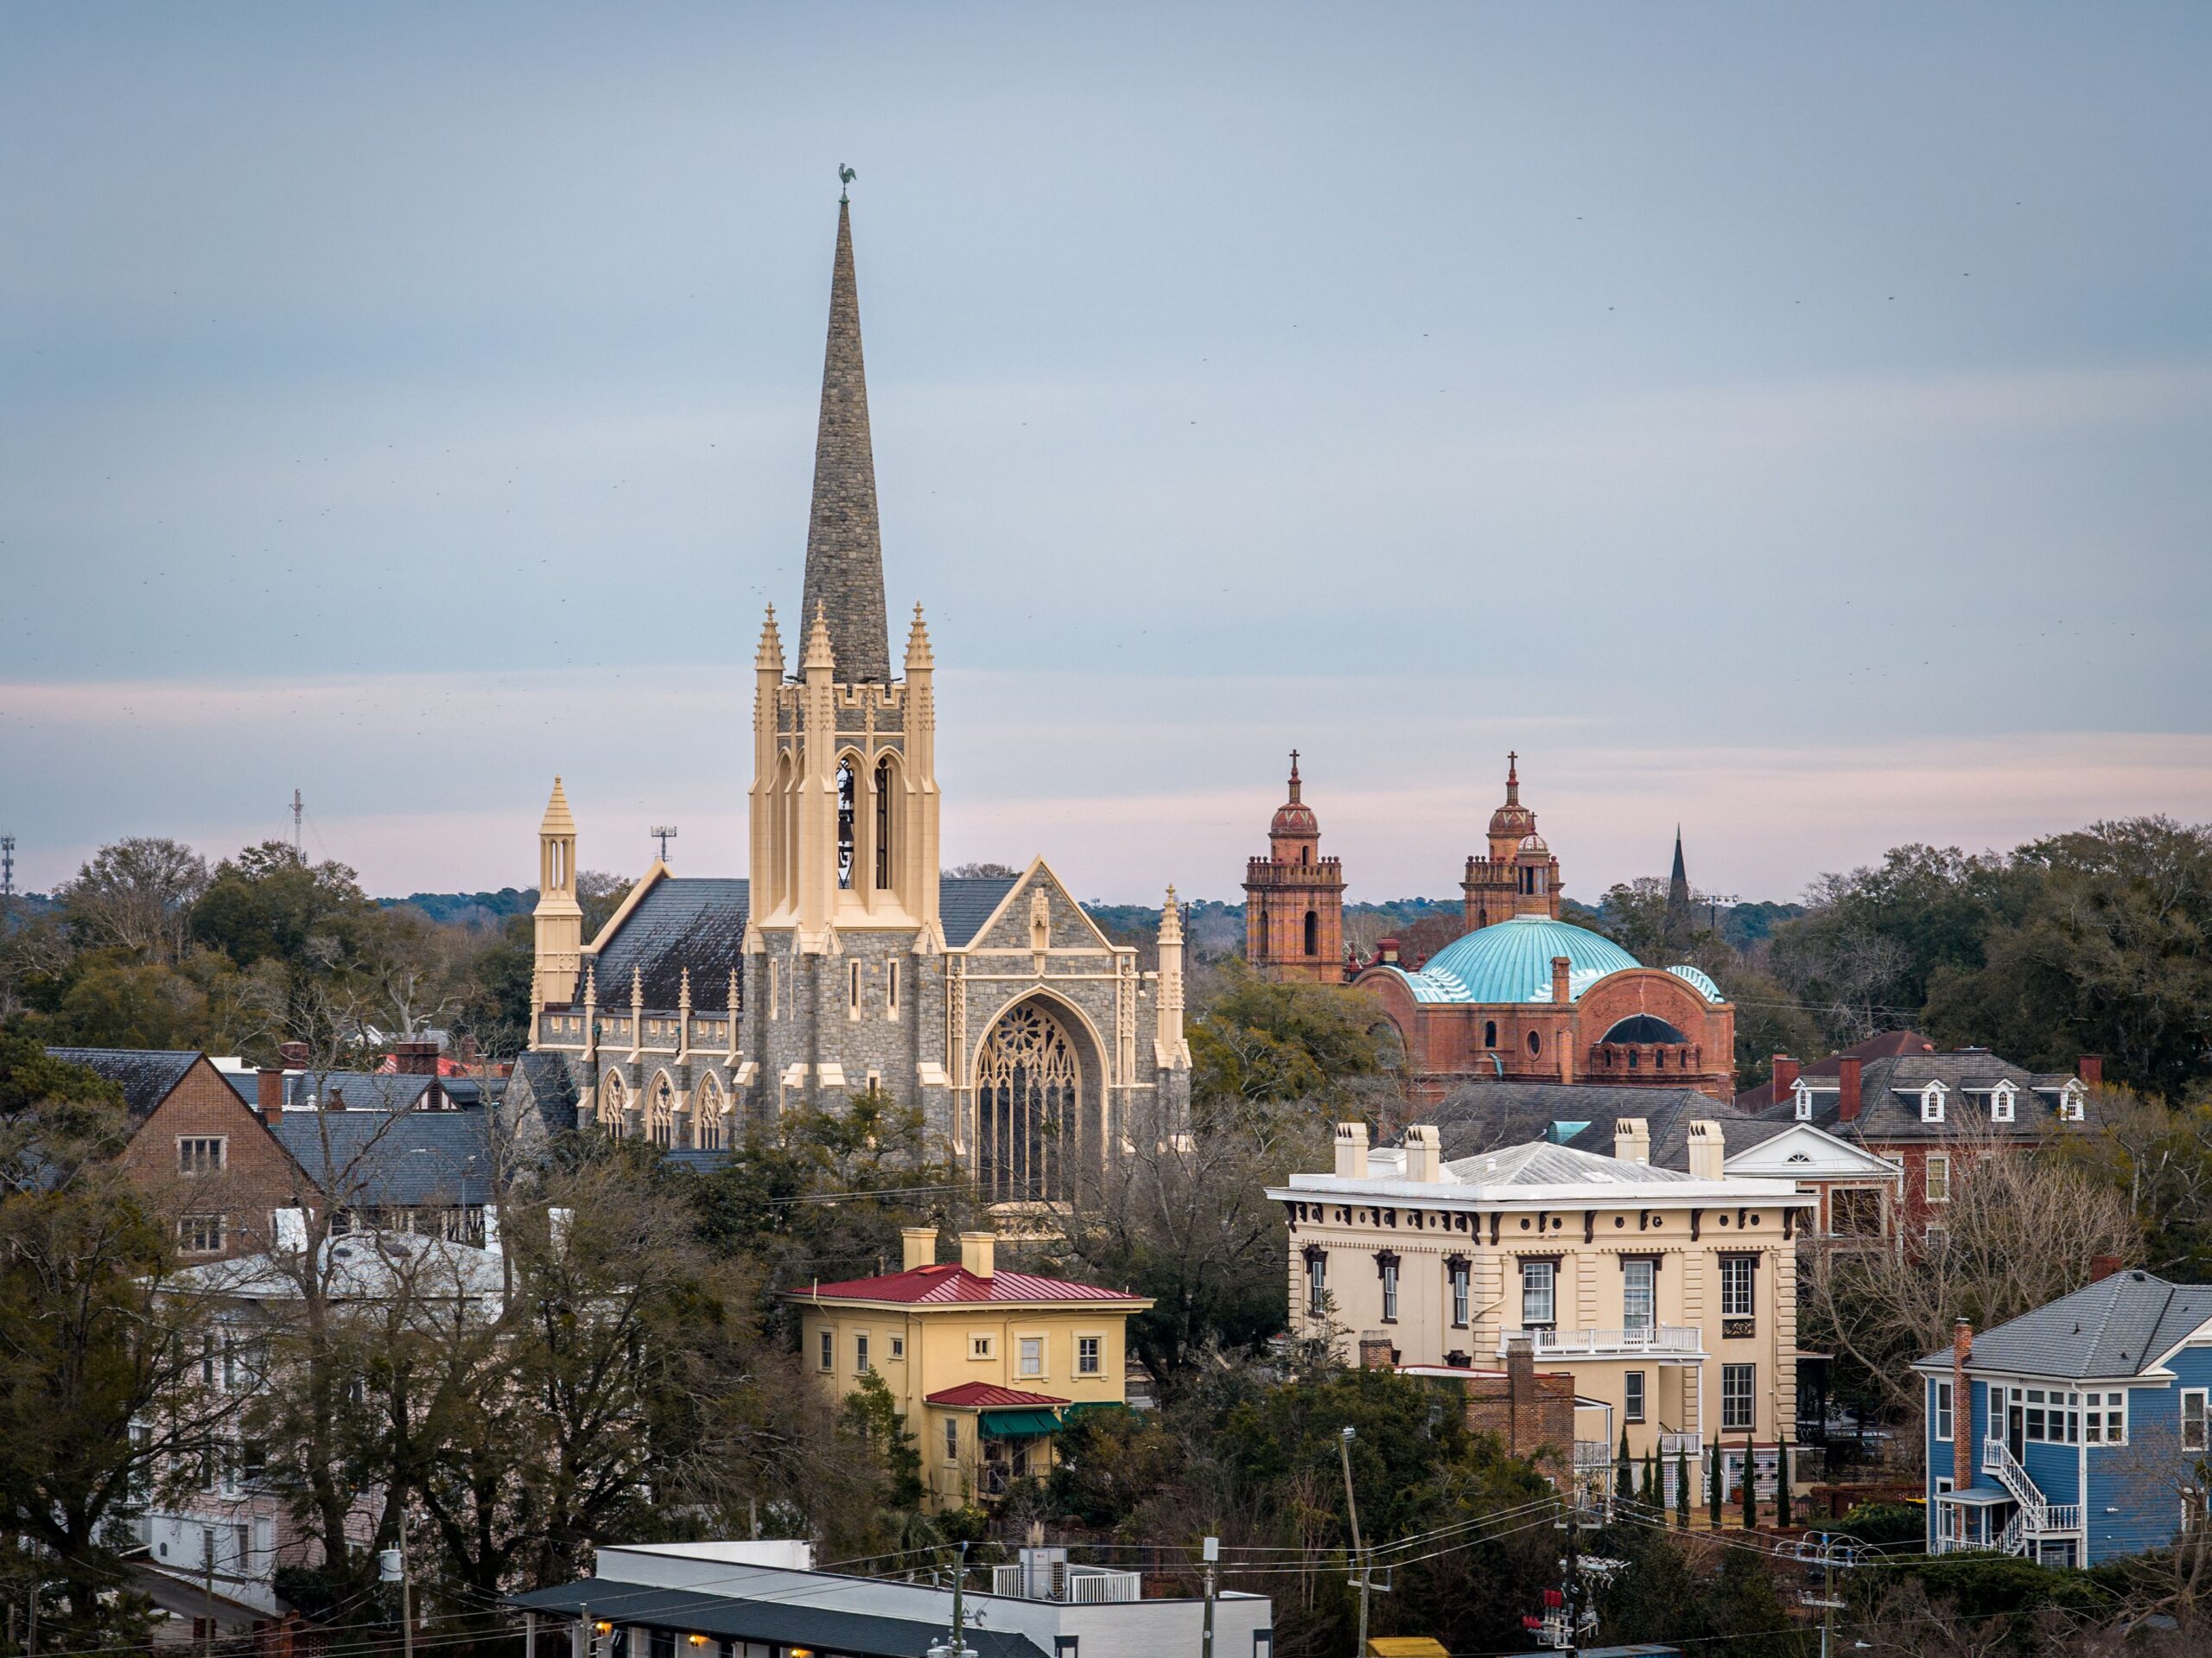
Buying inside Wilmington’s local historic district is a different transaction than buying almost anywhere else in New Hanover County. The house is only part of what you’re taking on — you’re also inheriting a set of rules about what you’re allowed to change on the outside of it, plus a narrower and often pricier set of insurance and financing options than a buyer choosing between Brunswick Forest and RiverLights will ever have to think about. Neither fact should scare a serious buyer away from Market Street, Nun Street, or the blocks around Carolina Place. But we tell every buyer who calls us about a listing downtown the same thing before they write an offer: read the Certificate of Appropriateness rules and call your insurance agent before you fall for the wraparound porch, not after.
This post walks through what actually governs a historic district purchase here — the difference between the National Register listing and the local designation that carries real legal weight, what the city will and won’t let you change on a home’s exterior without a hearing, and how coastal underwriters treat a 1920s frame house differently than a 2019 build in Autumn Hall.
What “Historic District” Actually Means Here
Wilmington’s downtown historic district was listed on the National Register of Historic Places in 1974, with a boundary expansion in 2003 that brought the district to roughly 1,070 acres and around 875 contributing buildings. That National Register listing is mostly an honor and a doorway to federal rehabilitation tax credits — it doesn’t, by itself, restrict what an owner can do to a house.
The layer that actually controls your renovation plans is the city’s local historic district designation, administered by Wilmington’s Historic Preservation Commission (HPC). It overlaps with the National Register boundary but isn’t identical to it, and nearby neighborhoods like Carolina Place and Carolina Heights carry their own separate local historic district designations with their own design review. Before you write an offer on anything with any age to it near downtown, we tell buyers to confirm which district — if any — the specific parcel sits in, because that determines whether a paint color or a new roof needs a permit or a hearing.
The Certificate of Appropriateness, in Plain English
Any exterior change inside a local historic district requires a Certificate of Appropriateness (COA) before work starts. The city splits these into two tracks, and the difference matters for how long your renovation timeline needs to be.
Minor Works
Storm windows and doors, fences, shutters, ADA access features, signage, awnings, garden sheds, rear decks, walkways, and some roof replacements can be approved administratively by city staff, without a hearing. The city’s current guidance says a complete application is typically reviewed within 7 to 10 business days.
Major Works
Additions, new construction, and more substantial or highly visible alterations go to the full Historic Preservation Commission for review at a public hearing. That means your renovation is on the commission’s meeting calendar, not just a staff reviewer’s desk, so build real weeks — not days — into any plan that touches a front-facing element of the house.
The detail that catches buyers off guard is what we’d call the after-the-fact problem: when you buy a historic district house, you also buy its compliance history. If a previous owner enclosed a porch, swapped in vinyl windows, or built a deck without ever pulling a COA, that liability doesn’t stay with them at closing — it transfers to you, and the HPC can require it to be undone. We tell buyers to have their agent pull the property’s COA and permit history from the city before the due diligence period ends, especially on any addition, deck, or window that doesn’t look original to the house.
Insurance on an Older Coastal Home
New Hanover County sits inside the 20-county coastal area covered by the North Carolina Insurance Underwriting Association, commonly called the Beach Plan, which is where wind and hail coverage for older homes often ends up when a standard carrier won’t write it directly. That’s separate from flood insurance, and separate again from the NCJUA (the state’s FAIR Plan), which acts as an insurer of last resort for basic fire and wind coverage on properties standard carriers decline outright. A century-old frame house with an original roof, knob-and-tube wiring still live in the walls, or galvanized supply lines is exactly the kind of property that can land in one of these pools instead of a standard homeowners policy.
Roof age is usually the first question an underwriter asks, and it carries more weight here than it does further inland. Exact cutoffs vary by carrier [verify], but a roof past 20 to 25 years old commonly triggers a wind-mitigation inspection or a higher deductible even when the shingles still look sound from the sidewalk. We tell buyers to get a roof-age estimate and a look at the electrical panel during the inspection period, not after — a declined binder a week before closing is one of the fastest ways a historic district deal falls apart.
Financing an Older House
Conventional and FHA loans both work fine on historic district homes, but appraisers tend to flag the same issues insurers do — outdated wiring, an aging roof, deferred maintenance on a porch or foundation — and some of those become repair conditions before the loan can close. If the house genuinely needs work, an FHA 203(k) loan or a conventional renovation loan lets a buyer finance the purchase and the repairs together. Budget real time for it, though: draws on a renovation loan for exterior work inside the historic district still have to clear a COA before a contractor gets paid, which stacks one approval process on top of another.
Downtown Versus the Newer Neighborhoods
None of this makes a historic district purchase a bad idea — it makes it a different one. A buyer who wants a walkable block near the Riverwalk and the shops on Front Street, in a house with real early-1900s architectural detail, is trading away the predictability of a newer build in Mayfaire, RiverLights, or Landfall, where there’s no HPC review, standard insurance underwriting, and a roof that isn’t old enough to worry about yet. Both are legitimate ways to live here, and we work with buyers choosing each side of that trade every month.
We just want a buyer looking at Carolina Place or the blocks off Market Street to go in knowing the porch railing they want to replace needs a sign-off, and the roof they’re inheriting might need a call to their insurance agent before it needs a call to a contractor. Buying downtown rewards patience more than it punishes it — most of the friction is procedural, not financial, and a buyer who lines up the COA history, the insurance quote, and the loan terms before writing an offer avoids almost all of it.
Matthew Kane, NC Broker #297432, Real Broker LLC (NC Firm #C34379). Phone: (910) 372-6720. Email: info@tidalrealtypartners.com.